

The ongoing AI rush produced many unlikely beneficiaries in semiconductors, photonics, infrastructure, and more. The most obvious beneficiaries have been the ones building the AI models that hundreds of millions use: most notably, OpenAI and Anthropic.
Unfortunately, these two are private companies and have been throughout their development. Most retail investors haven’t been able to invest in them as their stock price has 5x’d (OpenAI) and 22x’d (Anthropic).
However, this is soon to change. Both Anthropic and OpenAI are preparing to go public in the next couple of years, with Anthropic expecting to go public as early as October 2026.
Retail investors haven’t been able to invest in either AI giant, but companies have. Most big investors in OpenAI, like Microsoft, are so large that their multibillion dollar stake doesn’t affect their valuation much. However, some smaller companies invested early in Anthropic, and this has paid off handsomely.
Anthropic is now valued at $380B, but when SK Telecom invested $100M, it was worth just $5B. The stake is now over a billion dollars, as compared to their market cap of $13.9B.
SK Telecom currently trades at a discount to comparable peers due to past headwinds. Anthropic’s IPO can provide liquidity and a stronger balance sheet.
The looming question is: What is the core business of SK Telecom worth?
Before we explore this, we must understand SK Telecom’s business.
1. What All Does SK Telecom Do?
SK Telecom (NYSE: SKM) is a diversified South Korean MNO (mobile network operator) telecom business with recent expansion into higher growth fields such as enterprise AI solutions, internet, and data center infrastructure. In simple terms, SK is akin to America’s Verizon or AT&T, but is attempting to become a tech conglomerate through capitalization of AI demand.
The dominant cash engine is their wireless mobile service. It includes data plans and 5G/LTE subscriptions and encompasses roughly 53% of revenue. This segment of SK’s business is low-growth, but has a wide moat due to high switching costs, market leadership, and superior network ifnrastructure.
Fixed-line/broadband internet is SK’s second most profitable segment of business. Here, SK sells subscriptions for internet, TV, and business internet. This makes up roughly 28% of revenue and is also fairly low growth.
SK Telecom has many businesses listed as “Other” on their financial statements. This includes AI & digital platforms, enterprise solutions, E-commerce, AdTech, smarthome devices and the Seoul SK Knights, which play in the Korean Basketball League.1
This makes up a fairly small portion of revenue despite consisting of so many services. This is due to most of these services either being failed expansion or have growth underway. Their e-commerce segment has been loss-making for years and SK is trying to find a way to offload it. However, their AI solutions are quickly growing as South Korea’s AI expansion grows.
2. Competitive Landscape
Domestic Telecom
In South Korea, the telecom market is a highly concentrated three player market, with SK, KT, and LG U+ having a stronghold on the market. SK Telecom is positioned as the highest quality network. It has the highest ARPU (average revenue per user) and strong brand loyalty.
KT primarily focuses on the Broadband and home internet side of connectivity and uses that to bundle with mobile networks. KT is the leader in fixed-line and broadband dominance, with large enterprise and government presence.
LG U+ competes aggressively on pricing to win market share, as they are less established than the other two. LG U+ offers cheaper plans, flexible offerings, and targets younger users.
Over the past decade, market shares have hardly moved and all three maintain profitability. Innovation and disruption is not prevalent in this market, and it is likely that SK Telecom will maintain a small lead here.
Artificial Intelligence
The South Korea artificial intelligence landscape is much more interesting and complicated, as there are many elements of AI growth converging at once, and SKT is at the center of all of them.
SK is employing a three-pronged approach to artificial intelligence: data centers, enterprise AI, and consumer AI. This is a much more broad and ambitious strategy compared to KT’s and LG U+’s strategies on AI. Theirs are narrower, with KT focusing on enterprise AI and LG U+ on smart home strategies.
Data Centers
SK Telecom’s AI data center revenue grew 53% YoY, which shows their growing competitive position in the sector. This was driven by its GPU-as-a-Service partnership with Lambda and its Haein GPU cluster, which was recognized as the best cloud solution for 2026 at MWC Barcelona.
A key partnership to understand is that SK Telecom and SK Hynix are both under the same parent company, SK Inc. SK Hynix is a prominent manufacturer of semiconductors and SK can provide networking solutions for GPUs, so their partnership is very beneficial for data center buildout. Other telecom providers, like KT and LG U+ can’t compete with SK Inc.’s vertical integration.
Domestically, SK Telecom is far ahead in data centers, with $400M in annualized revenue and a strong Asian presence. SKT’s future positioning in the data center space is planned to include AIDC hubs across three major regions in Korea. The goal is to be a sovereign AI infrastructure model, instead of a regional, small player. However, their positioning today is strong locally, weak globally.
Enterprise AI
SK’s enterprise AI adoption has lagged behind competitors, but their reach is growing. SK has three AI agents: A-dot, Adot Biz, and Aster. A-dot is largely for local, personal use; Adot Biz for business and enterprise usage, and Aster for global personal usage. SKT’s B2B AI solutions have been deployed across 21 different SK affiliates, giving it a massive captive proving ground.
However, KT has a clear lead here. They began adoption with enterprises and the govenrment early, locking in a regulatory and switching cost moat. SK will be able to eat away at some of that market share, but this is largely KT’s domain.
AIX is SK’s biggest near-term revenue driver. It includes their Adot Biz, AICC (contact center), network optimization, and vision AI. SK is aiming to eat away at KT’s market share by providing specific AI use cases for AI, especially related to networking solutions.
In short, KT can create a business transformation with their enterprise AI solutions, while SK’s services can enhance current operations. It is unlikely that SK begins to gain significant market share here, although their revenue and adoption should grow nevertheless.
Consumer AI
SKT is well ahead of its competitors in consumer AI, although it is to be seen how large this market will be. Through their personal AI agent, A-dot, SK has gained 47% market share of the personal AI assistant space.
As compared to their two main competitors, LG U+’s ixi-O reached 150,000 subscribers by the end of 2024, while SK’s AI has reached 10.56 million users domestically, and KT’s GiGA Genie is primarily a voice-assistant product tied to home hardware.
There are some smaller players that have significant market share in the LLM space. SKT focuses on AI-powered voice bots and personal AI agents, while they fall behind in terms of LLMs. Naver and Kakao have most of the market share there, and as we’ve seen in America, people prefer LLMs to voice bots. That’s why ChatGPT has roughly 9x the weekly users of Amazon Alexa.
SKT is aiming to expand globally to North America. They partnered with Perplexity to release Aster, a personal AI agent similar to A-dot. It is currently still in beta phase and is expected to release later this year.
3. Catalysts and Risks
Catalysts:
South Korea’s continuing AI adoption
International rollout and adoption of Aster
Continued growth of SKT’s AIX enterprise presence
SKT’s data center buildout expanding throughout Asia
Anthropic’s IPO (SKT’s stake is currently worth $2B, and on the high end of IPO estimates nearly $5B)
Strengthened partnership between SKT and SK Hynix
After a previous dip in dividend payouts, restored dividends for 2026. The consistent dividend payout halted because of a cyber breach in early 2025, which required much of their available cash to handle
Risks:
Larger hyperscalers bypassing SKT and building out data centers themselves in Asia
KT’s continued grasp on the enterprise AI market
Competitive pressure on pricing from LG U+ or an emerging player on domestic telecom
Regulatory pressure from government demands to lower 5G tariffs
CapEx risks from large AI data center capacity
Delays in Aster’s rollout internationally
Continued fallout from 2025’s cyber attack
4. Valuation
To value a company like SK Telecom, one cannot simply apply a PE ratio and call it a day. To determine what percentage of SKT’s market cap the Anthropic stake represents, we first need to calculate the current value of that investment.
SK Telecom invested $100M into Anthropic in 2023. At the time, Anthropic was valued at $5B, and the stake was approximately 2% of the company. Through further funding rounds as Anthropic grew, SK’s stake was diluted significantly. Their stake is estimated to be between 0.4-0.7% of Anthropic now.
Anthropic is currently valued at $380 billion, making SK’s stake between 1.52B (0.4%) and 2.66B (0.7%). With an IPO estimated to be completed as early as October 2026, it is fair to say that Anthropic’s valuation will likely rise in anticipation. Estimates have ranged between its current $380B and $600B, which I will use for the bear and bull case.
Here are my estimates to the value of SKT’s stake in Anthropic. Note that the dollar amounts are in millions. The red section denotes Anthropic’s IPO price, and the blue section represents SK’s percent stake in Anthropic.
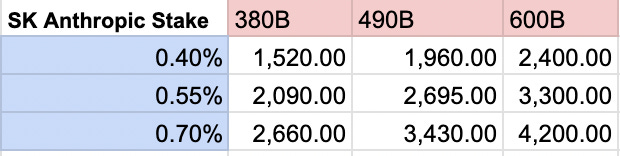
The midpoint of both Anthropic’s IPO and SK’s stake is $2.7 billion. To be more conservative and account for a potential post-IPO dip, I’ll round down to $2.5B. With a market cap of $13.43B, this makes up 19% of SKT’s market cap. The market is pricing SKT’s core business at $10.93B.
The primary valuation metric used to value Telcos is EV/EBITDA due to its neutralization of depreciation and capital structure. SK Telecom is a mature company, not likely to grow revenues significantly in the coming years, so using a discounted cash flow model isn’t necessary.
The cyberattack in early 2025 distorted last year’s numbers significantly. Revenue dipped 4.8% last year, while operating income dropped 41% and net income 73%. We can’t use these backwards-facing numbers to value SK, because the fallout has been largely resolved.
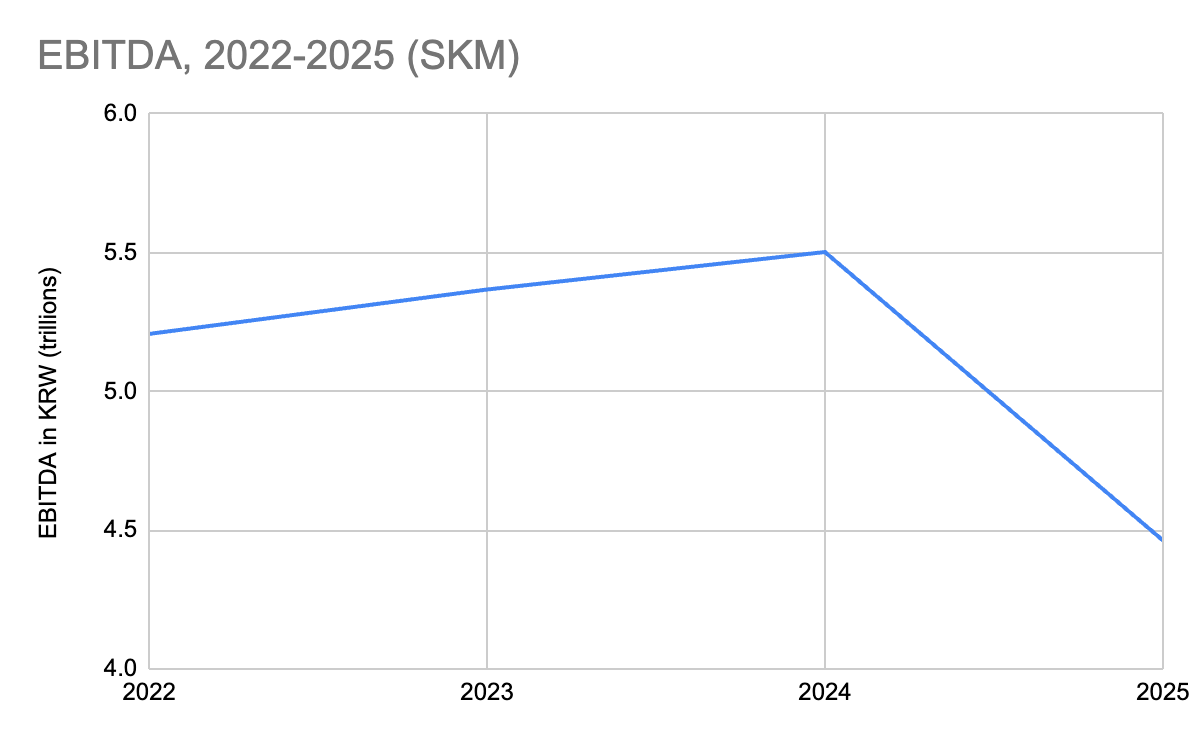
Let’s assume that EBITDA can rebound from these lows, but the growth pattern from 2022-2024 slows down. This is consistent with SK Telecom’s increased investment into AI and data centers, temporarily compressing earnings to prioritize the future. 5.2 trillion KRW is a conservative, but slightly optimistic estimate for SK’s EBITDA. 5.2 trillion KRW is $3.5B USD.
Removing SK’s stake in Anthropic from the equation, as we are only focused on SKT’s core business, gives an enterprise value of $16.82B. Fairly high long-term debt is the main contributor to SKT’s high enterprise value relative to their market cap.
These estimates give an EV/EBITDA of 4.8 (5.52 if you added back the Anthropic stake).
Now, we can compare to similar Telcos:
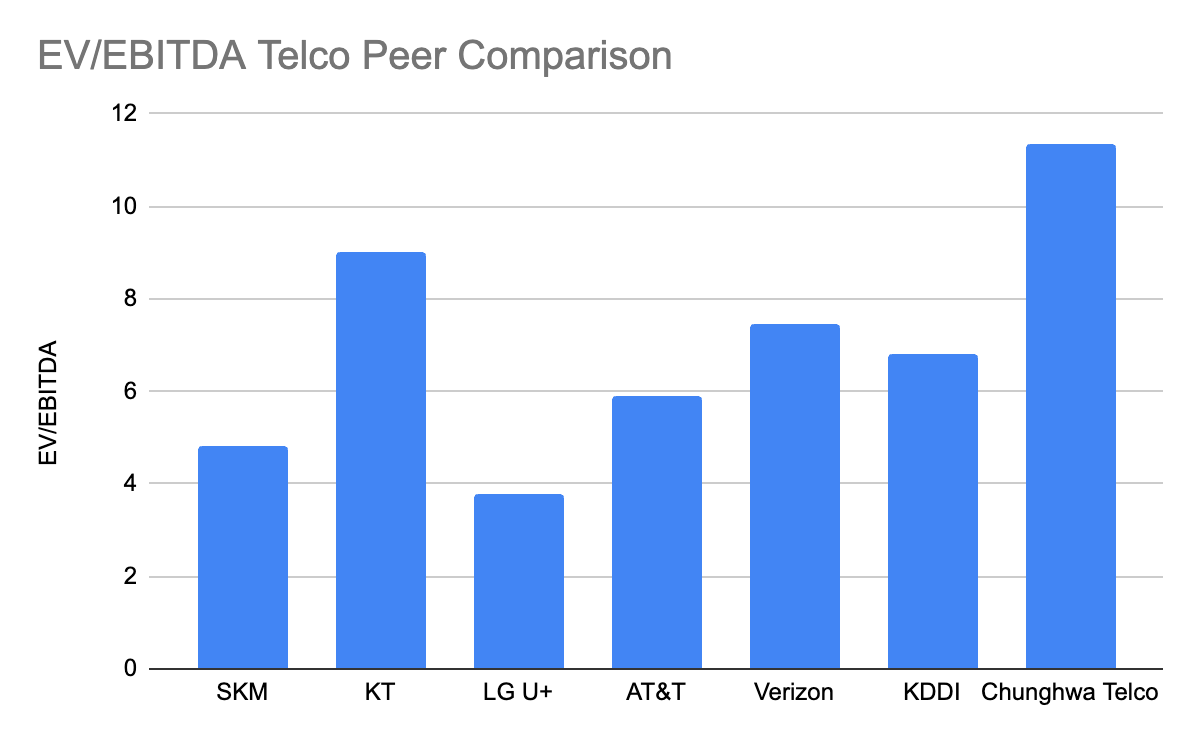
SK Telecom trades at the second-lowest EV/EBITDA multiple of the group. The only company with a cheaper multiple, LG U+, is a competitor in their home market, in which SK Telecom is the leader.
To trade at an EV/EBITDA multiple that aligns with its quality and market position, SK Telecom’s enterprise value would have to rise to $21B, a $4.12B rise from its current EV. This would require stock price appreciation of 31%.
This modeling does make some assumptions that should be noted:
It assumes that SKT’s core business will recover after the cyber attack that significantly impacted profitability in 2025
It assumes that SKT can capitalize properly off of Anthropic’s IPO. Even if Anthropic has its IPO at a $600B valuation, there is no guarantee that a sell-off will occur after Anthropic is listed, meaning that SKT would not be able to properly capitalize off of Anthropic’s high valuation. Still, I’d be surprised if SKT’s stake in Anthropic falls below my low end number of $1.5B, which still would lead to SKT trading at a significant discount to similar telcos.
Most credibly, it assumes that CapEx from data centers doesn’t continue to impact profitability like it has. It is likely that CapEx from this venture will continue, which should hurt profit margins. However, AI data centers are SKT’s fastest growing operation, which should negate this possible discrepancy.
5. Conclusion
On the surface, SKT might not appear to be undervalued relative to peers. Without accounting for their Anthropic stake and emergency-provoked EBITDA drop, SKT trades at 6.23 EV/EBITDA, which appears to be a fair multiple as compared to peers. However, when one takes into account these other factors, the picture becomes less clear, and SKT is portrayed as an undervalued company.
This is without pricing in the catalyst of successful AI data center growth in the East Asian region, which has been its fastest growing segment, albeit a low-impact one at the moment.
SK Telecom is a low-growth mobile network operator that’s priced like one. But the market may not be properly pricing in their future catalysts: most notably, Anthropic’s impending IPO and data center growth in East Asia.
Conduct your own due diligence, or consult a licensed financial advisor or broker before making any and all investment decisions. Any investments, trades, speculations, or decisions made on the basis of any information found on this site, expressed or implied herein, are committed at your own risk, financial or otherwise.
Bullseye Investing is my personal weblog. It reflects my own views, ideas and opinions. It is not a production of any employer, nor is it affiliated with any broker/dealer or registered investment advisor.
Samsung and KT, their competitors, also have basketball teams in the same league. In fact, all ten teams are owned by companies. Just like in business, SK beats Samsung and KT in basketball, as Samsung’s team finished last, KT’s finished seventh, and SK’s finished fourth. SK plays in the quarterfinals of the playoffs tonight at midnight (my time zone) at the time of this writing. This has nothing to do with the investment case, but I thought it was interesting
It is tempting to look for backdoors into hot AI companies like Anthropic, but getting access does not mean it is a smart investment. By the time everyday investors buy into these private unicorns through closed-end funds or secondary markets, the life-changing returns have already been made.
Recent data shows that Gulf sovereign wealth funds are dominating secondary sales, sweeping up old FTX stakes at massive premiums. Meanwhile, the cost to train next-generation AI models is expected to hit $10 billion this year alone.
Retail investors buying into these funds are rarely getting in on the ground floor. Instead, they are usually paying steep fees just to serve as exit liquidity for early backers who are cashing out at peak valuations. This "weird" way to invest might actually be the most expensive.
for a stake in OpenAI there is a loophole with $BMNR, as they’ve invested in EightCo which holds a direct stake in OpenAI serving as indirect ownership.
not sure on the numbers but it was decent. nice post bullseye 🎯